Key Points:
- ABA therapy insurance in Colorado follows different rules for state-regulated plans, self-funded employer plans, Health First Colorado, and TRICARE.
- Referral requirements and authorization periods depend on the payer, so families need the rules for their specific coverage.
- Two insurance policies require coordinated billing and do not automatically cover every service.
ABA therapy insurance in Colorado depends on your plan’s benefits, your child’s needs, and the approval rules for care. A covered ABA benefit does not tell you which provider you can use, what paperwork you need, or what your family will pay.
Your insurance card is a starting point. The next step is checking who sets your coverage rules. At Go Grow ABA, we help families review benefits for our ABA services in Colorado, including home sessions, assessments, and caregiver support.
 How Does Your Plan Type Affect ABA Coverage?
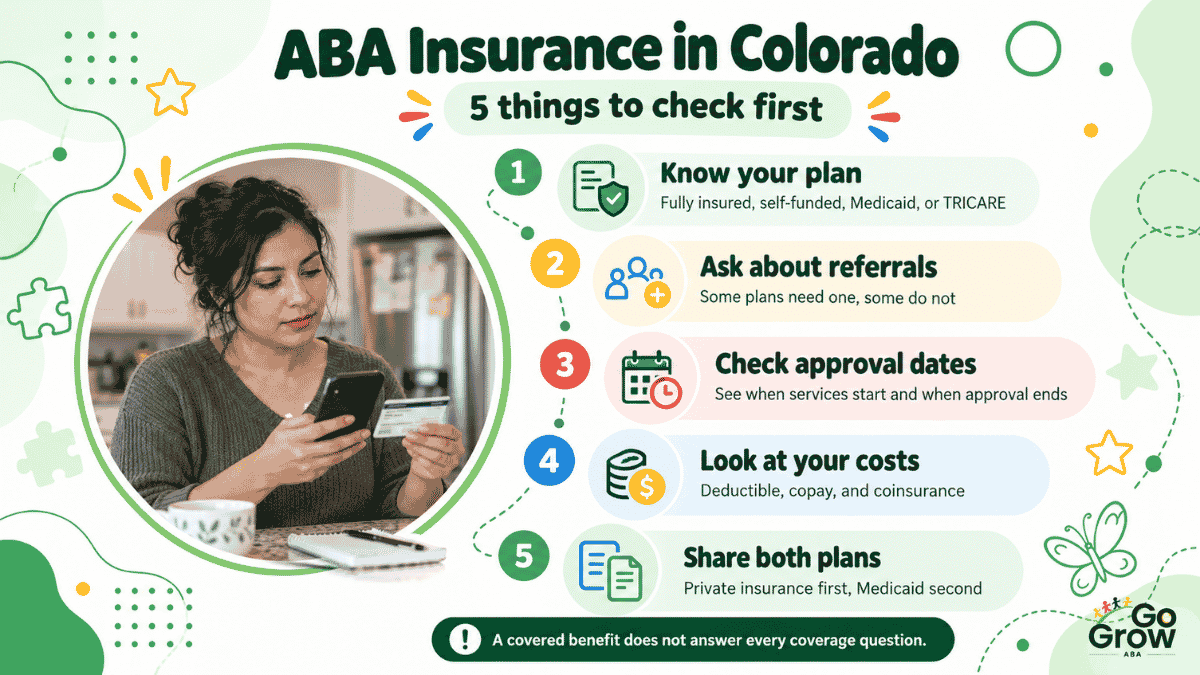
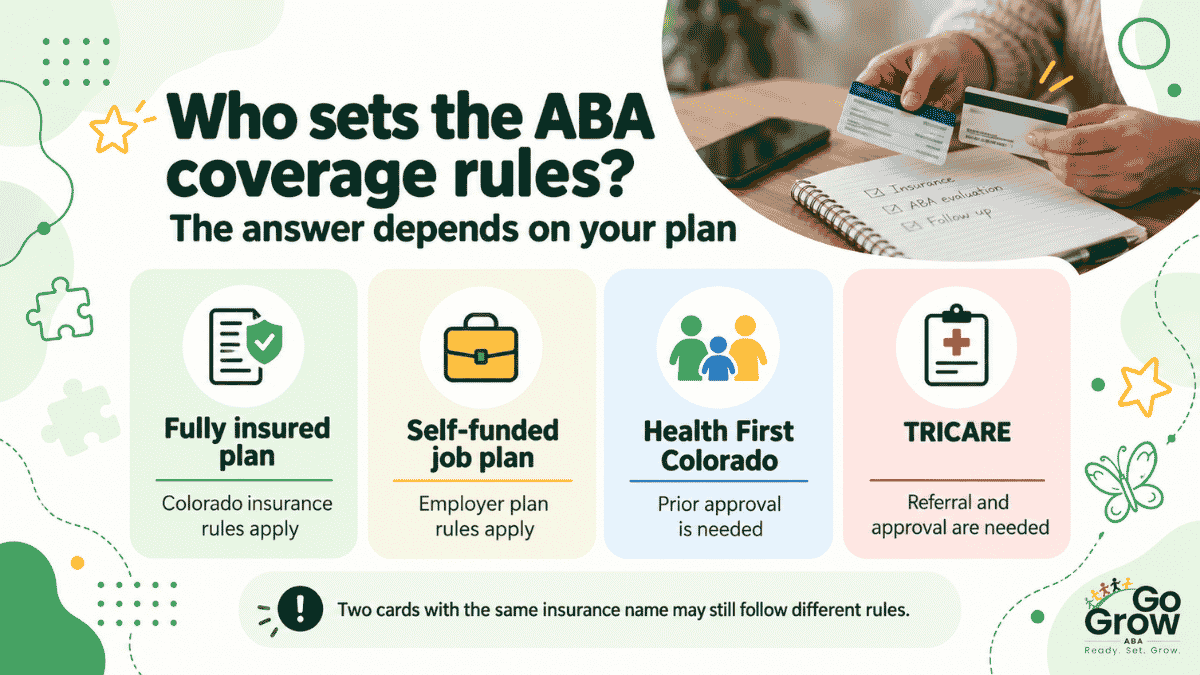
Your plan type determines which coverage rules apply. Two cards with the same insurance company’s name can represent different benefits.
| Coverage Type | Rules That Apply | First Detail to Confirm |
|---|---|---|
| Colorado-regulated, fully insured plan | Colorado insurance requirements and the policy’s terms | ABA benefits, network participation, and approval requirements |
| Self-funded employer plan | The employer’s plan documents and applicable federal requirements | Whether the plan covers ABA and how it reviews requests |
| Health First Colorado | Colorado Medicaid benefit and eligibility rules | Pediatric Behavioral Therapies requirements |
| TRICARE | Federal Autism Care Demonstration requirements | Program eligibility, referral, and authorization |
Colorado’s insurance mandates apply to fully insured plans under the Colorado Division of Insurance. Self-funded employer plans, Medicaid, TRICARE, and policies issued in other states follow different rules.
Colorado’s autism coverage law addresses autism assessment, diagnosis, and treatment, including ABA. Coverage requirements still allow applicable cost sharing and medical-necessity reviews.
For employer coverage, your human resources department or plan administrator can identify whether the plan is fully insured or self-funded. The Summary of Benefits and Coverage explains benefit and cost-sharing information; the full plan documents provide additional terms.
Referrals and Prior Authorization Follow Different Rules
A referral recommends or requests care. Prior authorization means the payer reviews a service before it begins. Your child may need both, depending on the coverage.
Commercial Insurance Requirements
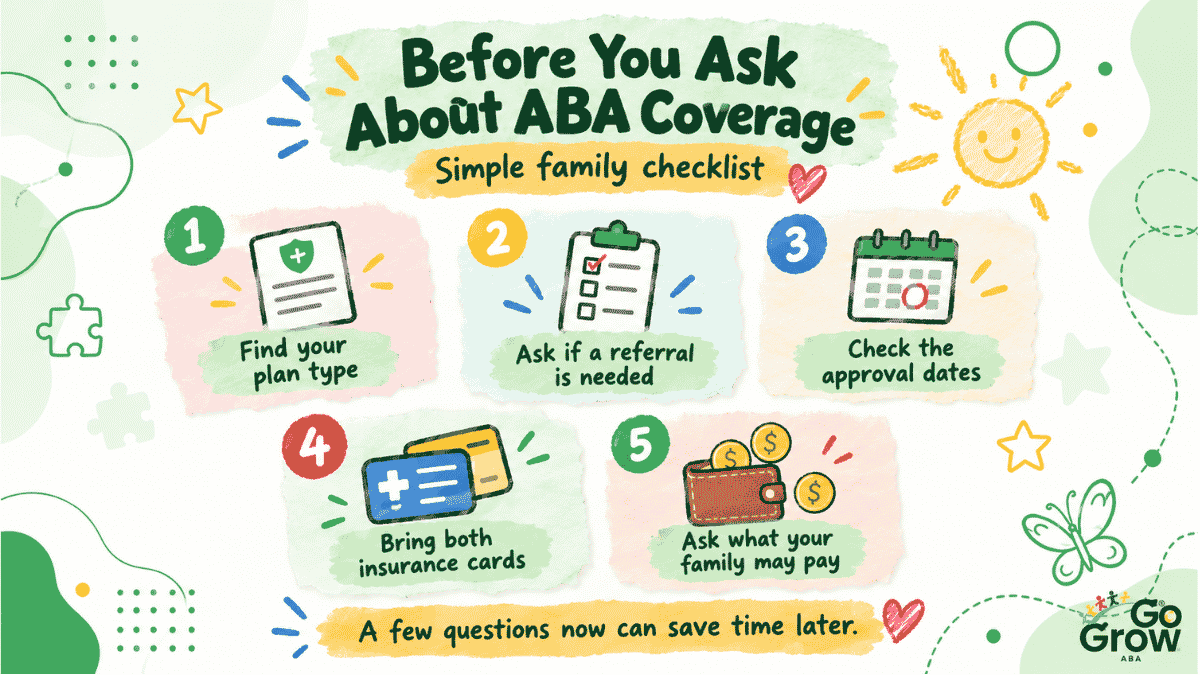
Commercial plans do not all use the same referral rules or approval periods. Your plan’s written ABA policy should answer:
- Diagnosis: Which professionals and diagnostic reports does the plan accept?
- Referral: Does the plan require a referral or prescription, and who can provide it?
- Assessment: Does the initial assessment need separate authorization?
- Treatment: Which records support the requested services, and when does approval expire?
These are details to confirm with your plan, not requirements that apply to every policy. A six-month approval period under another program does not establish your commercial plan’s renewal schedule.
Our ABA assessments help us identify treatment goals and develop a care plan. The payer separately decides which requested services meet its coverage requirements.
Health First Colorado Requirements
Health First Colorado’s Pediatric Behavioral Therapies benefit serves eligible members younger than 21 who meet its medical-necessity criteria.
The Pediatric Behavioral Therapies billing manual identifies physicians, physician assistants, nurse practitioners, and licensed psychologists as permitted sources of written orders, prescriptions, or referrals. A primary care physician is not the only permitted source.
When Health First Colorado is the primary payer, providers must obtain prior approval for Pediatric Behavioral Therapies. Requests include clinical records and treatment information. Approved periods can last up to six months, depending on medical necessity; the approval letter provides the actual dates.
TRICARE Requirements
TRICARE covers qualifying ABA services through its Autism Care Demonstration. Eligibility includes an autism diagnosis from an approved diagnosing provider.
All TRICARE plans require an ACD referral and authorization for ABA services. Initial assessment approval comes before the provider requests treatment approval. Treatment authorizations cover six-month periods, and ongoing care requires updated treatment information and outcome measures.
A new referral from the diagnosing provider is required every two years. That referral renewal is separate from the six-month treatment authorization. Active-duty families also have Exceptional Family Member Program and Extended Care Health Option enrollment requirements.
 What Could Your Family Pay for ABA Therapy?
Your family’s expense depends on covered services, network status, and your plan’s cost sharing. The provider’s billed charge, the insurer’s payment, and your responsibility are different amounts.
For commercial coverage, these terms help explain the estimate:
- Deductible: The amount you pay for certain covered services before the plan starts sharing those costs.
- Copayment: A fixed charge for a covered service.
- Coinsurance: Your percentage of the covered service’s allowed amount.
- Out-of-pocket maximum: The plan’s limit on qualifying member expenses for covered care.
A hypothetical example makes coinsurance easier to follow: after the deductible, 20% coinsurance on a $100 allowed amount would equal $20. Those numbers illustrate the calculation; they are not our rates or a coverage estimate. HealthCare.gov’s cost explanation shows how these amounts work together.
A written estimate should address the assessment, treatment sessions, and caregiver services separately. We include parent training in our services, so families considering caregiver coaching should check that benefit too.
The clinical recommendation for weekly ABA hours and the payer’s approval are separate decisions. A cost estimate should use the services actually approved and scheduled.
Two Insurance Plans Need Coordinated Billing
A child can have private insurance and Health First Colorado when eligible for both. Private insurance generally pays first, while Medicaid acts as the payer of last resort. HCPF’s member eligibility training explains that billing order.
Both coverage records belong with the provider. The billing team must check benefit rules, provider participation, and any authorization requirements that apply when Medicaid is secondary. Two active policies alone do not establish that every requested service is covered.
Health First Colorado members generally cannot be billed for covered services. A bill still deserves review, since some noncovered services can create a charge. The program’s steps for handling unexpected bills explain how to check responsibility before paying.
 FAQs About ABA Therapy Insurance in Colorado
What happens if an ABA request is denied?
The written denial should identify the reason and explain the next steps. Missing records may call for additional documentation; disagreement with a coverage decision may require an appeal. Health First Colorado’s member handbook explains its appeal process. Other plans have their own instructions and deadlines.
What if no in-network ABA provider has an opening?
Your insurer can help identify participating providers with availability. A follow-up request can address options when its directory produces no available appointments, including whether the plan offers a network exception. Written confirmation should establish the approved provider and cost sharing before an out-of-network visit.
Does a Health First Colorado authorization guarantee payment?
No. An approved authorization confirms the service’s benefit status, but payment also depends on eligibility and claim requirements. HCPF specifically states that prior authorization does not guarantee payment.
Review Your Colorado ABA Coverage With Our Team
Your plan documents, approval dates, and cost estimate each answer a different part of the coverage question. Together, they help your family prepare for care and understand possible expenses.
At Go Grow ABA, we provide in-home ABA, assessments, early intervention ABA, and caregiver support in Colorado. Our team can review your benefits and explain the next intake steps. A coverage inquiry can begin through our contact form or by calling (732) 554-8383.